
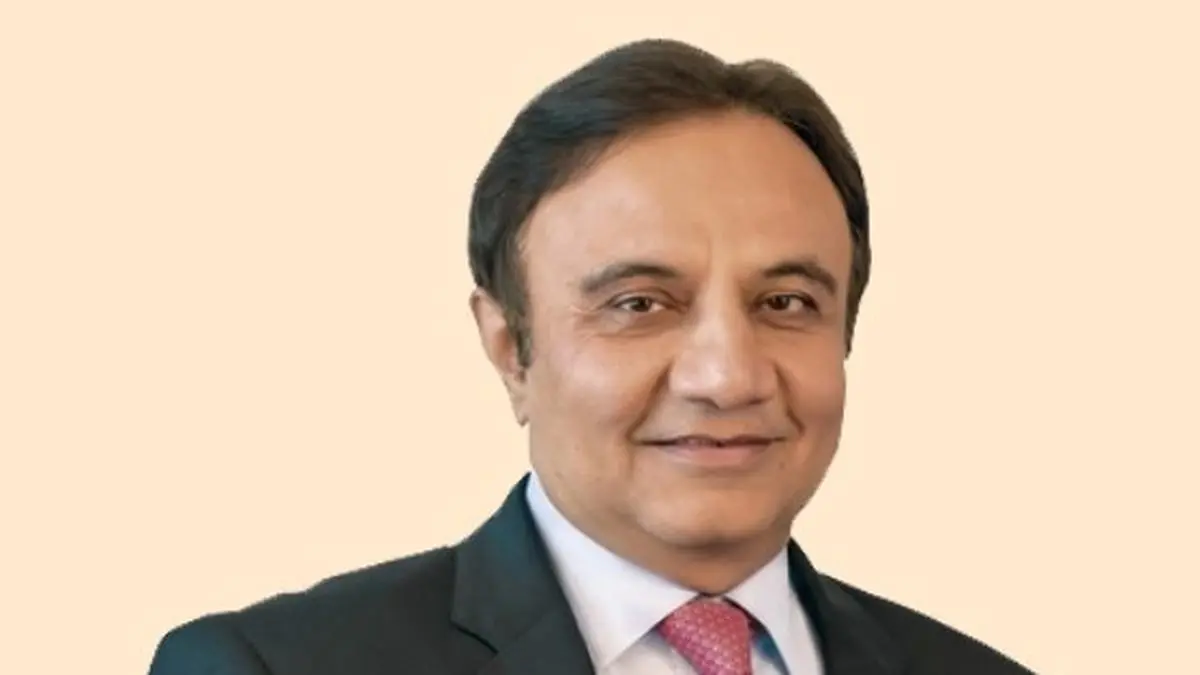
ICICI Bank shares remained in focus after the board approved a fresh two-year extension for Managing Director and CEO Sandeep Bakhshi. Analysts believe this move removes a long-standing uncertainty around leadership and improves investor confidence in the stock.
Although the bank reported mixed December quarter results, brokerages largely retained their positive outlook. Most analysts continue to recommend a ‘Buy’ rating, citing strong fundamentals and stable operating performance.
December Quarter Results Show One-Off Impact
ICICI Bank reported a 4 per cent year-on-year decline in net profit for the December quarter. The drop came mainly due to one-time provisions linked to agricultural assets.
Motilal Oswal Financial Services (MOFSL) said the bank’s profit missed its estimates by 9 per cent. However, net interest income (NII), pre-provision operating profit (PPOP), and adjusted PAT remained broadly in line with expectations. Margins also stayed stable during the quarter.
CEO Reappointment Removes Key Overhang
Analysts highlighted that the extension of Sandeep Bakhshi’s tenure till October 2028 is a major positive. The decision removes a key overhang that had been weighing on ICICI Bank shares.
MOFSL reiterated ICICI Bank as its top ‘Buy’ pick in the banking sector. The brokerage expects FY27 return on assets (RoA) at 2.3 per cent and return on equity (RoE) at 16.1 per cent. It revised its target price to ₹1,750.
Brokerages Remain Bullish on Growth Outlook
Nuvama said ICICI Bank avoided issues faced by peers like Axis Bank, as it did not need to declassify priority sector loans. The bank is working toward regularising its portfolio.
The brokerage maintained a ‘Buy’ rating and expects asset growth to accelerate. It also sees stable net interest margins and superior asset quality. Nuvama set a revised target price of ₹1,670.
Asset Quality and Growth Trends Stay Strong
Elara Securities noted that ICICI Bank’s core PPOP performance exceeded expectations. However, lower treasury income and higher credit costs affected quarterly profit.
The brokerage said growth momentum remains strong, while slippages stayed under control. Stability across key metrics added comfort, despite one-time RBI-mandated standard provisions.
Elara retained a ‘Buy’ rating with a target price of ₹1,783, factoring in valuation roll-forward to December 2027.
Valuation Comfort Supports Long-Term View
Nirmal Bang said ICICI Bank’s NII performance met expectations. However, PPOP and PAT fell short by around 5 per cent. Despite this, the brokerage maintained its ‘Buy’ rating with a target of ₹1,705.
Analysts agree that ICICI Bank has strong fundamentals and low risk of earnings disappointment. Leadership stability now strengthens its long-term investment case.
For more latest updates, click here.